

We Compare 100's of loans from leading lenders
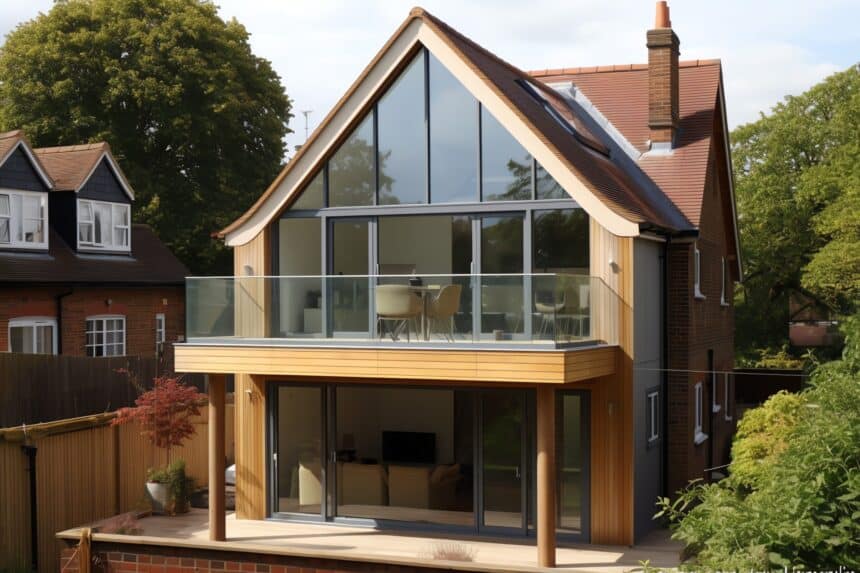
New-build and self-build properties can be used as security for a secured loan, although lenders may apply additional criteria depending on the age, construction and type of property.
One of the main considerations is the documentation available for the property. Depending on the lender, this could include an NHBC Buildmark warranty, Premier Guarantee, another acceptable structural warranty or a Professional Consultant’s Certificate (PCC).
At Willows Finance, we work with lenders that can consider new-build and self-build properties, including cases that may need to be referred because of the property’s construction type or the warranty or certification available.
If your property doesn’t fit a lender’s standard criteria, that doesn’t necessarily mean you can’t get a secured loan. Our advisers can check the details of the property and documentation against the criteria of the lenders we work with.
A new-build is generally a newly constructed property that has not previously been occupied.
New-build properties can include houses and flats purchased after construction, as well as properties originally purchased off-plan before the development was completed.
However, lenders don’t all use exactly the same definition of a new build. Some will continue to treat a property as a new build for a specified period after construction.
This can be important when applying for a secured loan because the age of the property can affect the lender’s loan-to-value (LTV), valuation and warranty requirements.
A self-build property is a home where the owner takes responsibility for arranging its construction, usually on land they own or have purchased.
This doesn’t mean you have to physically build the property yourself. You may manage the project or employ architects, surveyors, contractors and a building company to complete some or all of the work.
Once the property is complete, a secured loan lender will usually want to establish that the construction has been satisfactorily completed and that appropriate warranties or professional certification are available.
In This Guide
Other Categories
Yes. We work with lenders that can accept completed self-build properties as security for a secured loan.
The lender will want to understand how the property was constructed and whether it meets its property criteria.
If the property has a unique or non-standard construction type, this doesn’t automatically mean it will be declined. Some lenders may instead refer the property for individual consideration before confirming whether they are happy to accept it as security.
You may also be asked to provide documents relating to the construction and completion of the property. Depending on the lender, these could include:
An NHBC Buildmark warranty
A Premier Guarantee
Another structural warranty acceptable to the lender
A Professional Consultant’s Certificate (PCC)
An architect’s or other appropriate professional certificate
Details of the professional consultant’s indemnity insurance, where required
The exact documentation required will depend on the property and lender.
If you’re unsure whether the warranty or certificate you have will be accepted, our advisers can check it against lender criteria before your application progresses.
Yes. Most secured loan lenders can consider new-build properties, although their criteria can differ.
One of the differences between lenders is how they define a new-build property. This can depend on how recently the property was completed.
For properties built within the last 10 years, some lenders may ask for evidence of an acceptable building or structural warranty, such as an NHBC Buildmark warranty, or Premier Guarantee or equivalent.
Other documents or professional certification may also be acceptable depending on the lender.
The lender will also consider the property’s current market value, the amount of equity available and whether it meets their normal security requirements.
If your property doesn’t have an NHBC or Premier Guarantee warranty, don’t assume this prevents you from getting a secured loan. Other warranties or professional certification may be acceptable, or the case may be considered following a referral to the lender.
Maximum loan-to-value (LTV) limits can apply to secured loans on new-build properties, although the maximum available will depend on both the lender and the property. Most Standard new builds have the same LTV caps as any other standard property.
LTV is the amount of borrowing secured against your property compared with its value.
For example, if your property is worth £300,000 and the total borrowing secured against it after taking the new loan is £225,000, the combined LTV would be 75%.
When assessing the maximum LTV available, lenders may consider:
The current market value of the property
The amount of equity you have available
Whether the property is residential or buy-to-let
Whether it is a house or flat
How recently the property was completed
The warranty or professional certification available
Your existing mortgage and other secured borrowing
Your affordability and credit history
The maximum LTV can therefore vary considerably between applications.
Our advisers can check the property against different lenders’ criteria and explain the LTV options that may be available before you proceed.
Secured loan lenders may require evidence that a recently constructed property has an acceptable structural warranty or other suitable professional certification.
Two commonly recognised warranty providers are NHBC and Premier Guarantee.
However, having a warranty from a different provider doesn’t necessarily prevent the property from being accepted.
Depending on the lender, an alternative warranty may be accepted under its standard criteria or the property may be referred for individual consideration.
Some lenders may also consider a Professional Consultant’s Certificate (PCC) instead of a conventional structural warranty.
This is an area where lender criteria can vary significantly. If you tell us which warranty or certificate you have, we can check whether lenders on our panel are able to accept it.
Getting a quote won’t affect your credit score
Potentially. If you don’t have a conventional structural warranty, some lenders may accept an architect’s certificate or Professional Consultant’s Certificate (PCC).
A PCC is different from an insurance-backed structural warranty, so lenders don’t necessarily treat them in the same way.
Where a PCC or other professional certificate is being relied upon, the lender may want to establish who issued it, their professional qualifications and whether appropriate professional indemnity insurance was in place.
You may therefore be asked to provide both the certificate and a copy of the professional’s indemnity insurance details.
Some lenders will accept this type of certification while others may require a structural warranty, so the documents you have can influence which lenders are available.
If you only have an architect’s or Professional Consultant’s Certificate, let us know before applying. We can check which lenders may be able to consider it.
A standard secured loan may not be suitable while a property development is still under construction, but this doesn’t necessarily mean finance isn’t available.
There are lenders that can consider a bridging loan for a part-completed development.
The lender may want to understand:
The current condition and value of the development
The work that remains outstanding
The expected value once the work is completed
How the remaining building work will be funded
The planning and building documentation available
Any warranties, certificates or insurance-backed guarantees in place
A full valuation of the development may also be required.
Once the development has been completed, different longer-term finance options may become available.
If your property is currently part-completed, our team can establish whether a secured loan is appropriate or whether bridging finance is likely to be a better fit.

Yes. Most lenders can consider a barn conversion as security for a secured loan, provided the property meets their criteria and the appropriate documentation is available.
A barn conversion is typically an agricultural building that has been converted for residential use.
Because of the property’s previous use and the nature of the conversion, lenders may want to know more about the planning permission, building regulations, construction and legal work associated with the property.
They may also want to see an appropriate structural warranty, Professional Consultant’s Certificate or other evidence relating to the conversion, depending on when and how the work was completed.
Barn conversions can sometimes include unusual or non-standard construction features. Where this is the case, it doesn’t automatically mean the property will be unacceptable. Some lenders may refer the property or valuation for individual consideration.
The lender will also consider the property’s market value, condition, available equity and overall suitability as security.
If you own a barn conversion and are unsure whether it meets standard lending criteria, we can check the construction and documentation before identifying suitable lenders.
We’ve been helping people find mortgage deals since 2008, making it easier to find the best deal to suit their circumstances. Our team of experienced brokers provide free and friendly advice with no obligations and offer access to a huge range of deals. Whatever your budget we’ll work with you to find a deal that is tailored exactly to your needs
An NHBC Buildmark warranty, Premier Guarantee or another acceptable structural warranty
A Professional Consultant’s Certificate or architect’s certificate
Professional indemnity insurance details relating to the person who issued the certificate
Property valuation information
Planning or building regulations documentation
Documentation relating to the construction or conversion of the property
You won’t necessarily need everything listed above.
Our advisers can establish what documentation you already have and check it against the lender’s requirements, which can help avoid approaching a lender whose property criteria aren’t suitable.
New-build, self-build and converted properties don’t necessarily prevent you from getting a secured loan. The important thing is understanding the property and matching it with a lender whose criteria are suitable.
This becomes particularly important where you have an unusual construction type, an alternative warranty, a Professional Consultant’s Certificate or a property that needs to be referred for individual consideration.
At Willows Finance, we can look at the details of your property and the documents you have before searching our panel for lenders that may be able to help.
If the development is not yet complete, we can also explain whether bridging finance may be more appropriate.
Request a free quote or call Willows Finance on 01656 766 158 to discuss your property with one of our advisers.
If you have a question – we’d be happy to talk to you – simply call us…
(Mon-Fri 9am-8pm, Sat 10am-1pm)
Our Rating
At Willows Finance we ensure your personal information is kept secure and confidential.
PRIVACY OF YOUR INFORMATION
At Willows Finance Ltd, we appreciate that your privacy is extremely important to you. With this in mind, we have put in place a number of measures to ensure that any personal details we obtain from you as a result of visiting this website is processed and maintained in accordance with accepted principles of good information handling and also in accordance with the Data Protection Act 1988.
This statement provides you with details of the type of information we may hold about you, how we obtain and use information and how we protect your privacy.
Willows Finance Limited
Brocastle, Bridgend, CF35 5AS
Authorised and regulated by the Financial Conduct Authority
Firm Reference Number: 670052
Company Number: 06678545 (Registered in England and Wales)
This document explains the services we provide, the range of lenders and products we consider, how mortgage advice may be provided, and how Willows Finance may be paid. Please read it carefully before proceeding with an application.
If you need clarification about any part of this document, please contact us on 01656 766158.
Willows Finance arranges first and second charge mortgage products. Depending on the circumstances of the application, these may include:
We also arrange both regulated and unregulated bridging finance.
Not every product will be suitable or available to every customer. The products considered will depend on your circumstances, borrowing requirements, purpose of the borrowing, property, intended use of the property and the relevant lender criteria.
Depending on your circumstances, Willows Finance may:
If you are looking to increase borrowing secured on a property which already has a regulated mortgage, there may be different ways of raising the additional funds. Depending on your circumstances, these may include:
Where applicable, we will make you aware of these alternatives before proceeding. The options we are able to assess or advise on will depend on the service being provided and the lenders available to us.
The regulatory status of a mortgage or bridging loan depends on the circumstances of the transaction, including the property, how it is or will be occupied, the purpose of the borrowing and the customer’s circumstances.
Our business includes:
We will identify the regulatory status applicable to your application and explain the service and protections that apply. The protections available to you can differ depending on the type of mortgage or loan.
The range of lenders and products we consider depends on the type of finance you require.
We offer a comprehensive range of second charge mortgages from across the relevant market using a representative panel of lenders. We review our panel regularly to ensure that it remains sufficiently broad and representative. We do not consider products that are only available by applying directly to a lender.
We only offer first charge mortgages from a limited panel of 13 lenders. We consider the first charge mortgage products made available to us by Kensington Mortgages, The Mortgage Works, Aldermore, United Trust Bank (UTB), Together, Masthaven, West One, Norton, Bluestone, Vida, Pepper Money, Mansfield Building Society and Nationwide Building Society.
We do not offer every first charge mortgage available from across the market.
We consider products from a range of lenders available to Willows Finance for the relevant transaction.
Consumer Buy-to-Let and unregulated Buy-to-Let applications are considered within the relevant first charge, second charge or bridging route, depending on the structure of the transaction.
We do not provide a whole-of-market service and do not claim to consider every mortgage or secured finance product available in the UK. Our assessment is based on the lenders and products available through our lender and distribution arrangements.
Where the applicable regulatory rules require us to identify the lenders whose products we offer, the relevant lender list will be provided to you in a durable medium as part of the initial disclosure for your application. A lender list is also available on request where applicable.
The service provided will depend on the lender, product and application route identified for your circumstances.
Where Willows Finance provides the mortgage advice, we provide an advised mortgage broking service. We will obtain information about your needs and circumstances, assess the lending options available within the scope of our service and, where appropriate, make a mortgage recommendation.
We will make it clear where Willows Finance provides the mortgage advice and recommendation.
We may also provide a packaging service. This is a non-advised administrative service under which we may collect information and supporting documents, complete administrative checks, liaise with the relevant parties and submit or progress an application.
When we provide a packaging service, we do not assess the suitability of the mortgage, provide mortgage advice or make a personal recommendation. Any regulated mortgage advice or recommendation will be provided by the appropriately authorised intermediary responsible for advising you.
Our packaging service is not a regulated advisory service. However, the mortgage itself and any arranging activity connected with it may still be regulated and subject to the applicable regulatory requirements. We will explain the nature and regulatory status of the service we are providing before you proceed.
For some applications, particularly certain second charge mortgage applications, our sourcing exercise may identify a route where the subsequent mortgage advice is provided by another regulated mortgage intermediary.
In these cases, the Willows Finance service may include:
After the introduction, the receiving intermediary may take over the detailed application, advice and recommendation process. We will make it clear where this type of referral arrangement applies.
Where our sourcing process identifies Evolution Money Limited as an appropriate route and we introduce your application to Evolution Money, Willows Finance will not provide the regulated mortgage advice or make the final mortgage recommendation in relation to the Evolution mortgage.
Following the introduction, Evolution Money Limited will take over the detailed application and advisory process. Evolution Money will assess your needs and circumstances and will be responsible for any regulated mortgage advice and recommendation it provides in relation to the Evolution mortgage.
Willows Finance remains responsible for the service it provides before and in connection with the referral, including its initial assessment, sourcing and introduction activity.
If you are experiencing financial difficulty, or if you are considering borrowing to consolidate existing debts, free and impartial debt advice is available from MoneyHelper and other free debt-advice organisation.
MoneyHelper: www.moneyhelper.org.uk
You should consider obtaining free debt advice if you are unsure whether further borrowing or debt consolidation is right for you.
We process your personal information in accordance with our Privacy Policy. Where we introduce you to a lender or another intermediary, that organisation will process your information in accordance with its own privacy information.
Willows Finance Privacy Policy: willowsfinance.co.uk/privacy-cookie-policy/
The way Willows Finance is paid depends on the lender, product and application route. We may receive a fee paid by you, commission paid by a lender or another third party, or a combination of these. We will explain the basis on which we will be remunerated in connection with your application.
Where Willows Finance off an advised service our fees are split into two parts. A fee for the advice you receive and a fee for the processing of the application to completion. Both of these fees can be added to the loan rather than paid upfront or you have the option of paying them in advance. We do not arrange loans below £10,000.
For the advice the fee is as follows;
For a first charge mortgage, our advice fee is 5% of the amount borrowed, subject to a minimum fee of £625 and a maximum fee of £1,250.
For a second charge mortgage, our advice fee is 5% of the amount borrowed, subject to a minimum fee of £625 and a maximum fee of £1,750.
For a first charge mortgage, our processing fee is 5% of the amount borrowed, subject to a minimum fee of £625 and a maximum fee of £1,250.
For a second charge mortgage, our processing fee is 5% of the amount borrowed, subject to a minimum fee of £625 and a maximum fee of £1,750.
| Service | First charge | Second charge |
|---|---|---|
| Advice fee | 5%, min £625, max £1,250 | 5%, min £625, max £1,750 |
| Processing fee | 5%, min £625, max £1,250 | 5%, min £625, max £1,750 |
On borrowing of £10,000 5% would be £500, but the minimum fee for advice and processing means that we would charge £625 for each to £1250 in total.
On borrowing £20,000 the total fees would be £2,000
On borrowing £50,000 the maximum fee means that we would charge a total of £2500 for a 1st charge mortgage and £3500 for a 2nd charge mortgage.
If your mortgage or loan completes following an introduction made by Willows Finance, we will receive commission from the lender or another third party in the distribution chain unless we tell you otherwise. Different lenders may pay different amounts and may use different commission models.
Commission models may include:
The availability or amount of commission does not determine which lender we consider appropriate for your circumstances. Where applicable, we will tell you that commission will be received.
For an MCD regulated mortgage (a mortgage within the Mortgage Credit Directive rules), where the exact amount of commission is not known at the time of the initial disclosure, we will tell you that the actual amount will be disclosed later in the ESIS. Where applicable and on request, we will also provide information about how commission levels vary between lenders offering the mortgage being considered.
Where we introduce you to Evolution Money, the commercial arrangement is different from a broker fee charged directly by Willows Finance.
Under the current Evolution arrangement, Evolution Lending charges a Product Fee equal to 10% of the net loan advance, subject to a maximum of £5,000. If the mortgage completes, Evolution pays the corresponding amount to Willows Finance as commission/remuneration for the sourcing, distribution and introduction service.
The amount of the product fee and the amount of remuneration payable to Willows Finance will be disclosed to you in the relevant mortgage documentation before completion.
Example: on a £10,000 net advance, a 10% Product Fee would be £1,000. The actual Product Fee and the amount of commission payable to Willows Finance will be set out in the relevant Evolution mortgage documentation before completion.
If you choose to add a Product Fee or other fee to your mortgage, interest will be charged on that amount while it remains outstanding, increasing the total amount you repay.
Where a Willows Finance fee is payable only on completion, it will not become payable if the mortgage does not complete. Any fee payable before completion, third-party costs and the circumstances in which a fee is refundable or non-refundable will be explained where applicable.
Fees which have become payable following completion are generally non-refundable unless the relevant contractual terms, applicable law or regulatory redress require otherwise.
Before you become bound by a regulated mortgage, you will receive the relevant mortgage illustration or European Standardised Information Sheet (ESIS) and the lender’s offer documentation as applicable.
These documents contain important information about the proposed mortgage, which may include:
Please read these documents carefully. If anything is unclear or does not reflect your understanding, contact the firm responsible for the advice or recommendation before proceeding.
You may tell us that you no longer wish to proceed with an application before completion. Whether any third-party cost is payable or refundable will depend on its own terms.
For an MCD regulated mortgage (a mortgage within the Mortgage Credit Directive rules), the lender will provide a binding offer with a reflection period of at least seven days. You may normally accept the offer during that reflection period if you decide to proceed.
Once a mortgage has completed, there is generally no right simply to cancel or withdraw from the mortgage. You may have a right to repay the mortgage early in accordance with its terms, and an early repayment charge may apply.
Always check the early repayment section of the ESIS and mortgage offer before completion if early repayment or regular overpayments are important to you.
If you miss or make late payments, the lender may apply charges, and your credit record may be affected. Continued failure to maintain payments may result in enforcement action and ultimately repossession of the property used as security.
If you are experiencing financial difficulty, contact your lender as soon as possible and consider obtaining free independent debt advice.
Consolidating existing debts into a mortgage can reduce monthly payments but may increase the total amount of interest you pay if the borrowing is repaid over a longer period.
Debts which are currently unsecured may become secured against your home. Extending the repayment period may mean that you pay considerably more overall even where the monthly payment is lower.
Interest rates on variable-rate mortgages can increase, which may increase monthly repayments and the total amount repaid.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR OTHER LOAN SECURED ON IT.
If you are dissatisfied with any aspect of the service provided by Willows Finance, please contact us:
Willows Finance Limited
Brocastle, Bridgend, CF35 5AS
Telephone: 01656 766158
Email: [email protected]
We will investigate your complaint in accordance with our complaints procedure. If you remain dissatisfied with our final response, or in other circumstances where you are eligible to do so, you may be able to refer your complaint to the Financial Ombudsman Service.
Financial Ombudsman Service: www.financial-ombudsman.org.uk
Where another regulated intermediary has provided the mortgage advice or recommendation, complaints about that firm’s advice should normally also be raised with that firm. You can still complain to Willows Finance about the service provided by Willows Finance.
The Financial Ombudsman Service can generally consider complaints about regulated or otherwise covered activities, including certain activities that are ancillary to them. It may not be able to consider a complaint that relates solely to an unregulated product or service and has no connection with a regulated or otherwise covered activity. Whether a complaint falls within its jurisdiction will be determined by the Financial Ombudsman Service based on the individual circumstances.
Willows Finance Limited is covered by the Financial Services Compensation Scheme for eligible regulated activities. If an authorised firm is unable to meet an eligible claim, compensation may be available from the FSCS.
For protected home finance mediation, the current compensation limit is 100% of an eligible claim up to £85,000 per eligible claimant, per firm. Eligibility depends on the circumstances of the claim and the applicable FSCS rules.
FSCS protection does not generally apply to a claim arising solely from an unregulated product or service, including any packaging service that falls outside regulated home-finance mediation. Whether a claim is eligible will depend on its individual circumstances and the applicable FSCS rules.
Further information: www.fscs.org.uk
Once we have received sufficient information about your circumstances and requirements, we will carry out the relevant initial assessment and sourcing process and explain which application route applies to you.
Where Willows Finance provides the mortgage advice, we will continue through our advised mortgage process and explain any recommendations made.
Where your application is referred to another regulated intermediary, such as Evolution Money, we will explain that the receiving intermediary will take over the subsequent application and advisory process where applicable.
Please review all mortgage illustrations, ESIS documents, fee and commission disclosures, offer documents and other terms carefully before deciding whether to proceed. If anything is unclear, ask before committing to the mortgage.
Let us know what you're looking for today